
Categories
Buying Strategy, Selling StrategyPublished September 22, 2026
Assuming a VA Loan in Austin: The Move Almost Nobody's Talking About
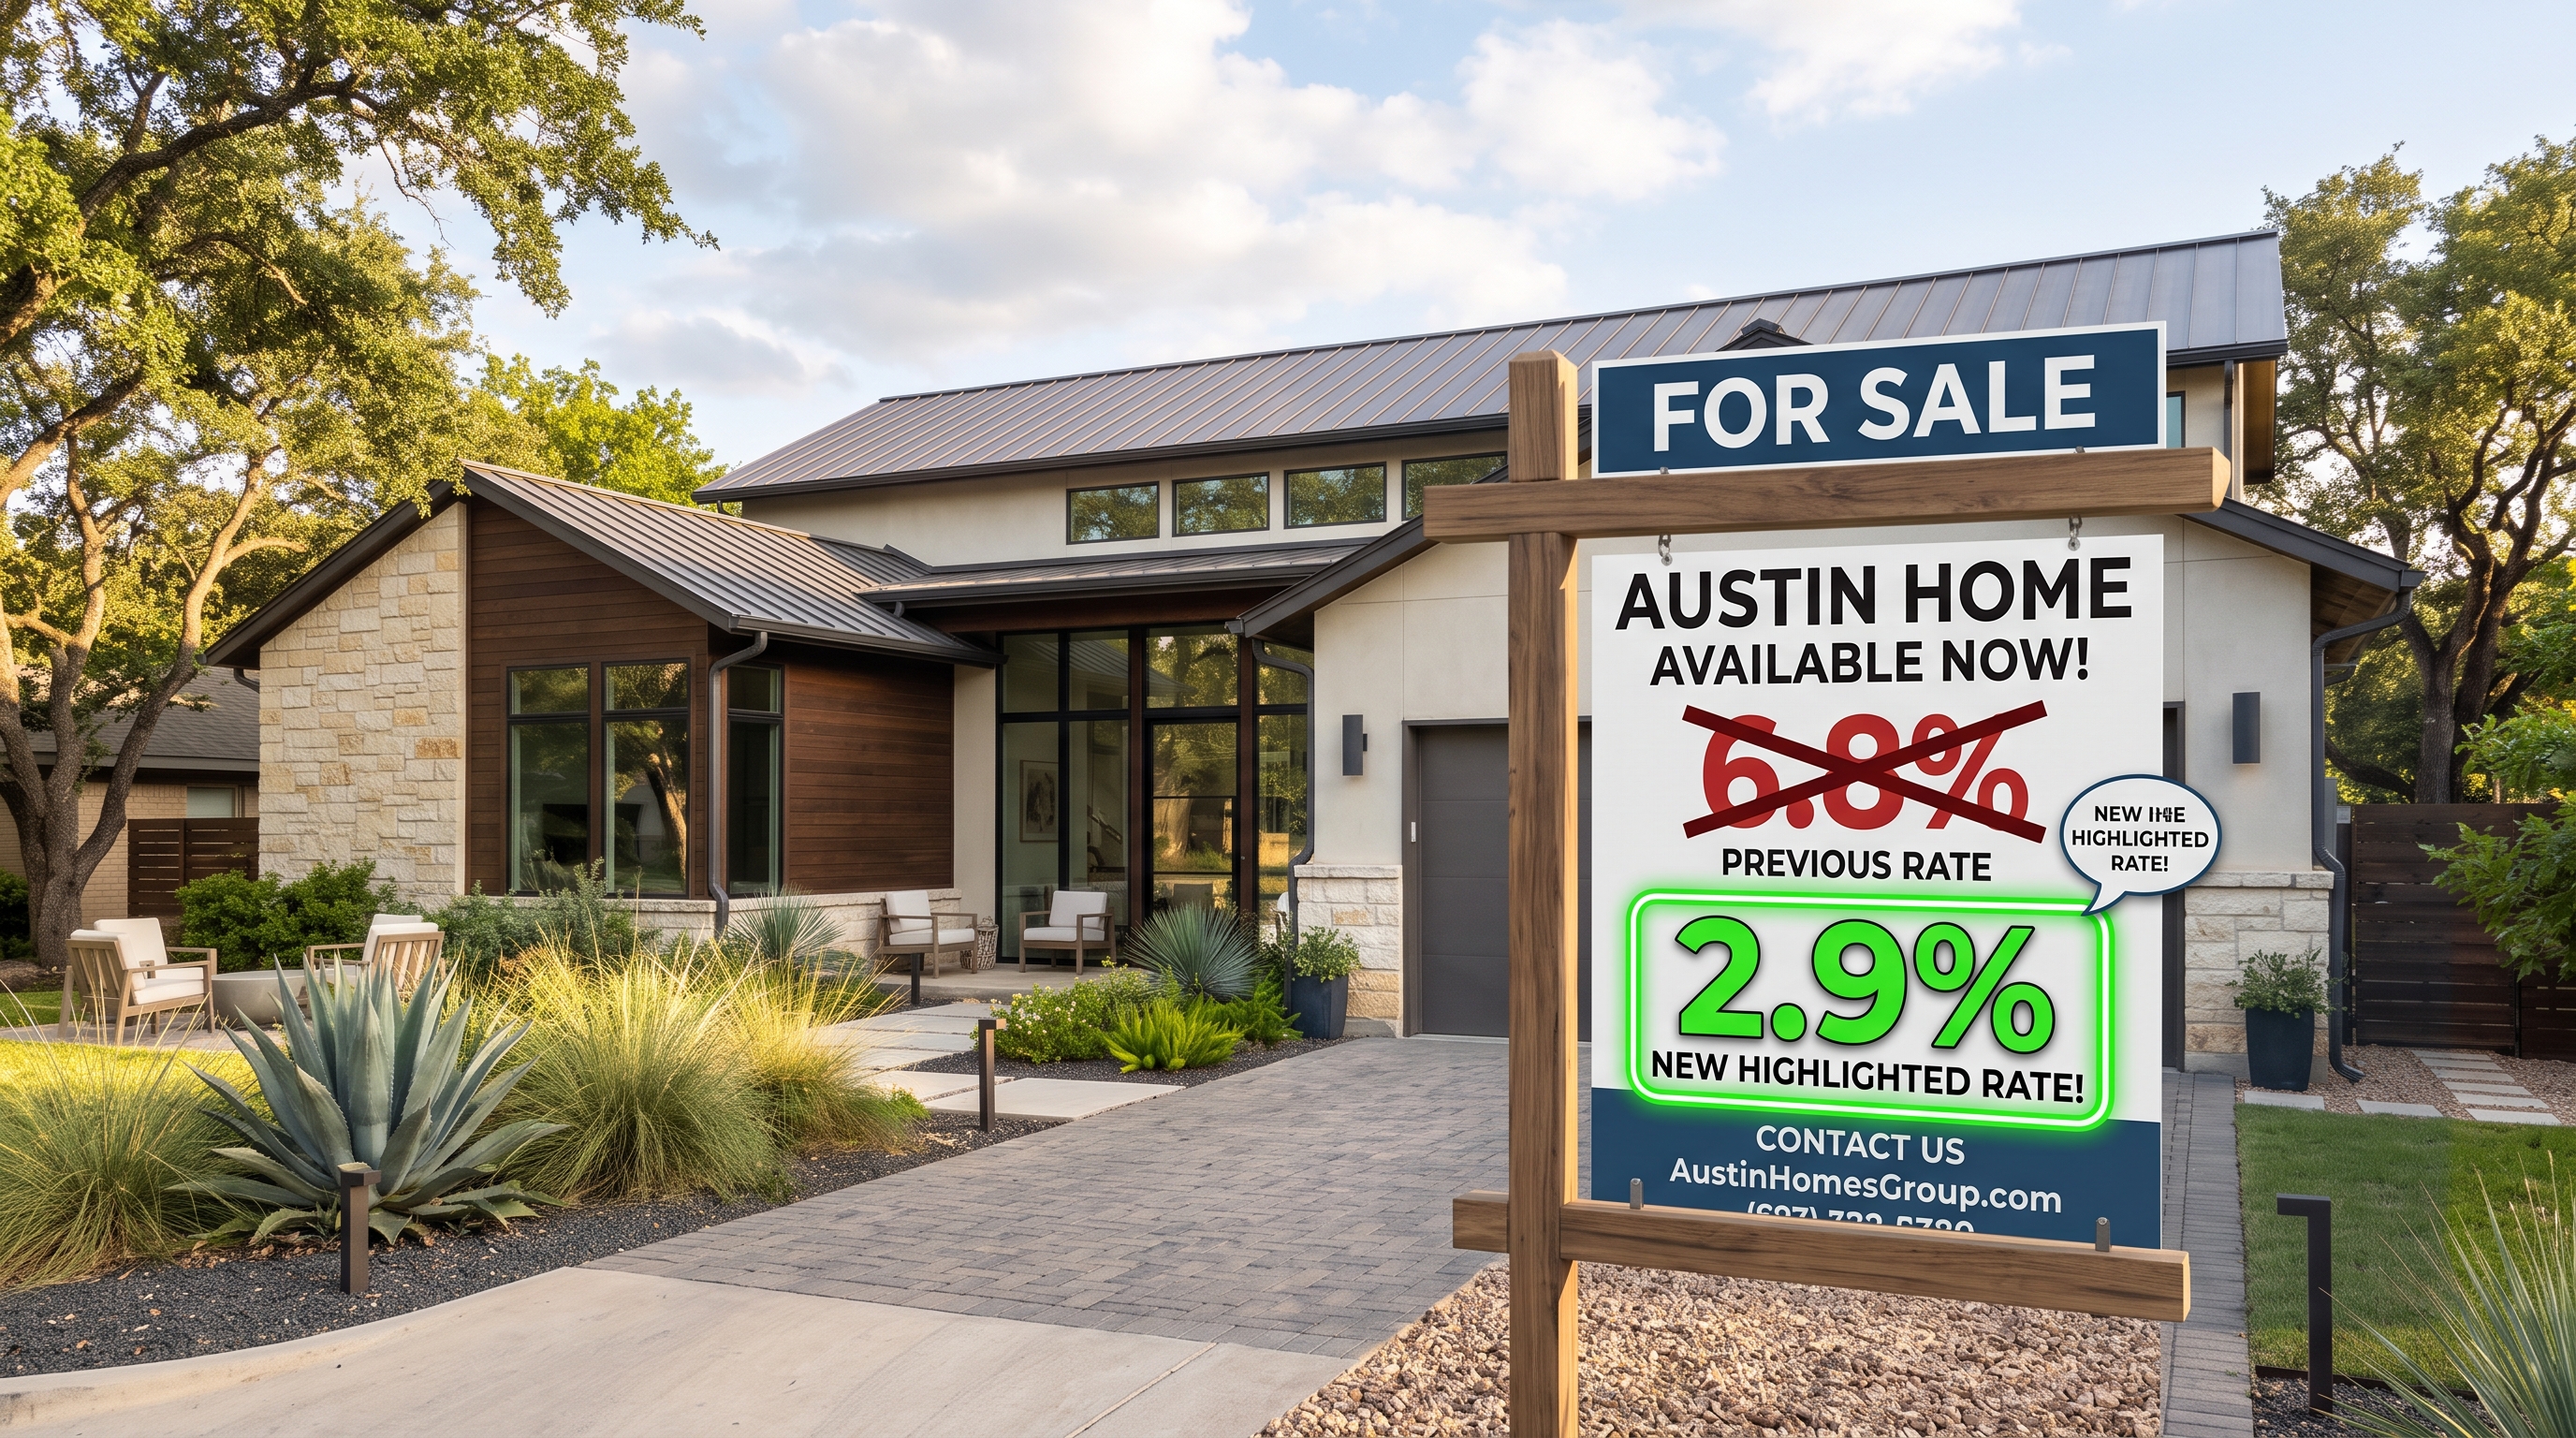
If a seller bought their Austin home between 2020 and 2022 with a VA loan, they may be sitting on a rate in the 2.5% to 3.5% range. A buyer can take over that loan, rate and all, instead of getting new financing at today's 6.8%. It's called a VA loan assumption, and you don't have to be a veteran to do it. At Schmitz & Smith Group, we've started building this into how we position certain listings and how we advise buyers who are priced out by current rates.
Why This Matters in Austin Right Now
- Current mortgage rates sit around 6.8%, while VA loans originated in 2020 to 2022 often carry rates under 3.5%
- Austin's price correction, with median sold prices down about 24% from the May 2022 peak, has narrowed the equity gap on many of these homes, making assumption more realistic than it was a year ago
- Most buyers and even a lot of agents don't know this option exists, which means less competition for buyers who do
What Buyers and Sellers Should Consider
- The equity gap: You pay the seller the difference between the loan balance and the sale price, either in cash or through a second loan. A smaller gap means less cash needed upfront.
- The timeline: VA loan servicers typically take 60 to 90 days to process an assumption, longer than a standard close. Both sides need to plan for that.
- Entitlement substitution: The seller's VA entitlement is tied up in the loan until the buyer substitutes their own entitlement or the loan is paid off. Sellers should understand this before they agree to an assumption.
- You don't need to be a veteran: Any qualified buyer can assume a VA loan. You still need to meet the lender's creditworthiness standards.
- Not every VA loan is assumable the same way: Loans originated after certain dates have different assumption rules. Confirm the specifics before you build a strategy around it.
Neighborhood Spotlight: Where This Comes Up Most
This works on any VA loan regardless of neighborhood, but it shows up more often in areas with a higher concentration of newer construction from the 2020 to 2022 building boom, where VA financing was common among first-time buyers and military families relocating to Austin.
Real Client Insight
Recently, I helped my buyers make an offer on a home in Allendale with an assumable VA loan with a 2.13% mortgage rate. Needless to say, the bids became very competitive and multiple offers came in quickly. Eventually, the person who got the house didn't want the assumable mortgage, so they may have been paying cash, but it definitely enticed several buyers to submit offers over asking price within the first few days of the house going live on the MLS.
Related Reading
- Is Buying a Home in Austin Still Affordable? (What Buyers Need to Know in 2026)
- First-Time Home Buyer 101: What to Expect (Without the Overwhelm)
- Moving to Austin in 2026? Do NOT Sign This Form Yet
Frequently Asked Questions About VA Loan Assumptions in Austin
? Do I have to be a veteran to assume a VA loan?
No. Any buyer who qualifies with the lender can assume the loan. The VA loan benefit stays tied to the original borrower's eligibility, not the new buyer's.
? How much cash will I need to cover the equity gap?
It depends entirely on the seller's remaining loan balance versus the sale price. On homes bought closer to the 2022 peak, that gap has narrowed significantly since prices corrected.
? Why does this take longer than a normal closing?
The loan servicer, not just the lender, has to process and approve the assumption. Budget 60 to 90 days instead of the usual 30 to 45.
? What's the risk for the seller?
Their entitlement stays tied up until the buyer substitutes their own or the loan is paid off. That can affect the seller's ability to buy their next home with a new VA loan.
? Is this worth pursuing as a buyer right now?
If you find a home with an assumable rate 3 to 4 points below current rates, the monthly savings can be substantial. It's worth the extra timeline and paperwork.
If you're a buyer trying to make the math work at today's rates, or a seller wondering whether your VA loan is a selling point, let's talk through it. The Schmitz & Smith Group works with buyers and sellers across Central Texas, including Hyde Park, Westlake, Barton Creek, Tarrytown, Dripping Springs, and beyond. Reach out anytime. 512-466-5224
or another way